Race to the Register: How Energy Developers Are Scrambling to Capture IRA Benefits Before the Window Closes
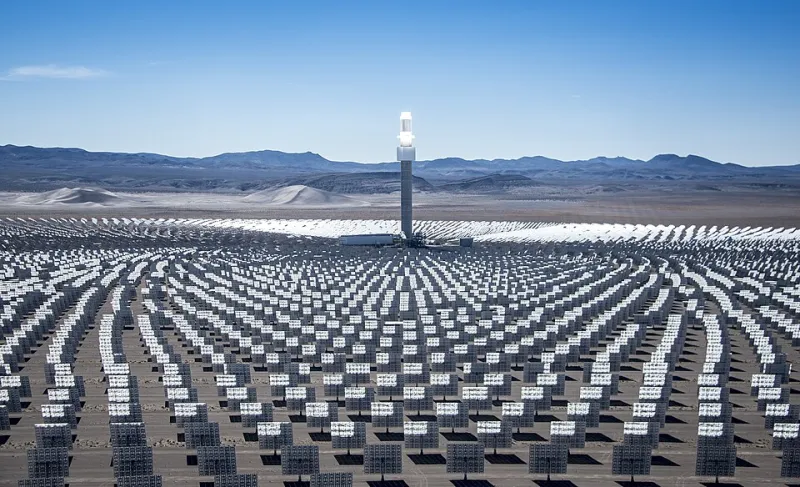
Photo: BLM Nevada, CC BY 2.0, via Wikimedia Commons
When Congress passed the Inflation Reduction Act in August 2022, it handed the American energy sector something it had long struggled to secure: a long-dated, technology-neutral incentive framework designed to underwrite the clean energy transition for a decade or more. Yet barely two years into the program's life, many developers are behaving as though the clock is already running out.
Across the industry, project timelines are being compressed, applications are being filed ahead of schedule, and legal teams are working overtime to interpret Treasury guidance in the most favorable terms possible. The implicit logic is straightforward: lock in what you can, while you can. What is less straightforward are the downstream consequences of an entire sector operating under that assumption simultaneously.
The Mechanics of the Rush
The IRA's clean energy provisions—spanning the Production Tax Credit, the Investment Tax Credit, bonus adders for domestic content and energy communities, and the newly transferable credit structure—represent the most significant federal support for energy investment in a generation. But the law's implementation has been anything but settled. Treasury and the IRS have issued guidance in waves, with some provisions still awaiting final rules. Meanwhile, the political environment has introduced persistent uncertainty about whether future administrations or Congresses might curtail, reinterpret, or rescind portions of the framework.
For energy developers, that uncertainty has produced a specific behavioral response: front-loading. Companies are racing to reach the milestones that lock in credit eligibility—beginning construction, establishing continuous work, placing projects in service—before interpretive guidance tightens or political conditions deteriorate.
"The incentive structure is generous, but it is not guaranteed," said one senior project finance attorney who advises utility-scale solar and storage developers across the Southeast. "Our clients are not being reckless. They are being rational. If there is a credible probability that the rules change in eighteen months, you move your timeline forward."
That rationality, multiplied across hundreds of developers, has produced something that looks less like orderly market development and more like a concentrated surge.
When Speed Becomes a Liability
The consequences of compressed timelines are beginning to surface in ways that deserve closer scrutiny. Procurement decisions that would ordinarily involve extended vendor qualification processes are being abbreviated. Engineering and design reviews that benefit from iteration are being shortened. In some cases, projects that might otherwise have spent another year in development—refining site control, completing geotechnical studies, resolving community engagement issues—are being advanced prematurely to meet internal deadlines driven by incentive calendars rather than project fundamentals.
Quality concerns are not hypothetical. Several large-scale solar installations completed under accelerated timelines in 2023 have already reported performance shortfalls attributed to installation deficiencies and equipment mismatches. While no single failure can be attributed solely to the incentive rush, industry observers note that the pressure to move fast is compressing the margin for error that good project development depends upon.
Beyond individual project quality, the aggregate acceleration is creating market distortions that affect the entire supply chain. Equipment lead times, already extended by post-pandemic logistics disruptions and domestic content requirements, are being strained further by a synchronized demand surge. Labor markets in key construction trades are tightening in ways that push up wages and, in some regions, constrain the availability of qualified crews entirely.
"You have a situation where the incentive structure is theoretically designed to lower the cost of clean energy deployment, but the behavior it is inducing is, in certain respects, raising it," noted one infrastructure investment analyst at a firm with a significant renewables portfolio. "That is not an argument against the IRA. It is an argument for thinking carefully about how policy design interacts with developer behavior."
The Domestic Content Gamble
Few provisions of the IRA have generated more strategic maneuvering than the domestic content bonus adder, which offers an additional ten percentage points of credit value to projects that meet specified thresholds for American-manufactured components. The financial stakes are substantial—on a utility-scale project, the difference between qualifying and not qualifying can run into tens of millions of dollars.
The problem is that the domestic manufacturing supply chain for solar modules, wind components, and battery storage systems is still in the process of being built. Several major facilities announced with considerable fanfare in 2022 and 2023 are only now beginning to reach commercial production scale. Developers who committed to domestic content compliance early have found themselves navigating a supplier landscape that is simultaneously expanding and unreliable.
Some have responded by structuring contracts with domestic content contingencies. Others have accepted the risk of falling short of the threshold and are prepared to forgo the adder if supply does not materialize. A smaller number have made representations about domestic content eligibility that legal observers describe as optimistic interpretations of ambiguous guidance—a posture that carries audit and recapture risk down the line.
What Happens After the Rush
The more consequential question may not be what happens during the incentive race, but what happens after it. The IRA's production and investment tax credits are structured to phase down beginning in the early 2030s, contingent on emissions thresholds in the electricity sector. If the transition proceeds as intended, the credits sunset as the economics of clean energy stand on their own. If it does not, the incentive framework will face a different kind of political pressure.
In either scenario, developers who have built their business models around a specific incentive stack will need to recalibrate. Those who have invested in genuine cost reduction—supply chain efficiency, construction productivity, technology performance—will be better positioned than those who have relied on the incentive margin to make marginal projects viable.
"The IRA creates a window, not a permanent condition," said one energy sector strategist who advises both developers and institutional investors on long-term capital allocation. "The companies that use this window to build durable competitive advantages will be in a fundamentally different position than those who use it simply to accelerate the queue."
That distinction—between strategic use of incentives and dependence on them—may ultimately define which participants in the current build-out emerge with lasting market positions and which find themselves exposed when the policy environment, as it invariably does, changes.
Governing the Rush
For policymakers and regulators, the developer behavior now visible across the market raises questions worth addressing directly. If the IRA's incentive structure is producing a rush that compromises project quality and distorts supply chains, there may be value in administrative mechanisms that smooth the deployment curve—phased guidance rollouts, capacity-based allocation windows, or enhanced audit frameworks that create accountability for performance representations.
None of those interventions would be costless, and all would require careful design to avoid introducing new distortions. But the alternative—allowing the current surge to proceed without any structural check—carries its own risks, both for the quality of the infrastructure being built and for the credibility of the policy framework that is funding it.
The Inflation Reduction Act remains, by most serious assessments, a transformative piece of energy legislation. Its long-term impact will depend significantly on whether the investment it catalyzes is channeled into projects that deliver durable value—or whether the race to capture its benefits leaves behind a trail of underperforming assets and exhausted market participants. That outcome is not yet determined. But the decisions being made in project development offices and investment committees across the country right now will go a long way toward writing it.