Coal's Last Bid: How Plant Owners Are Rushing to Extract Value Before the Regulatory Clock Runs Out
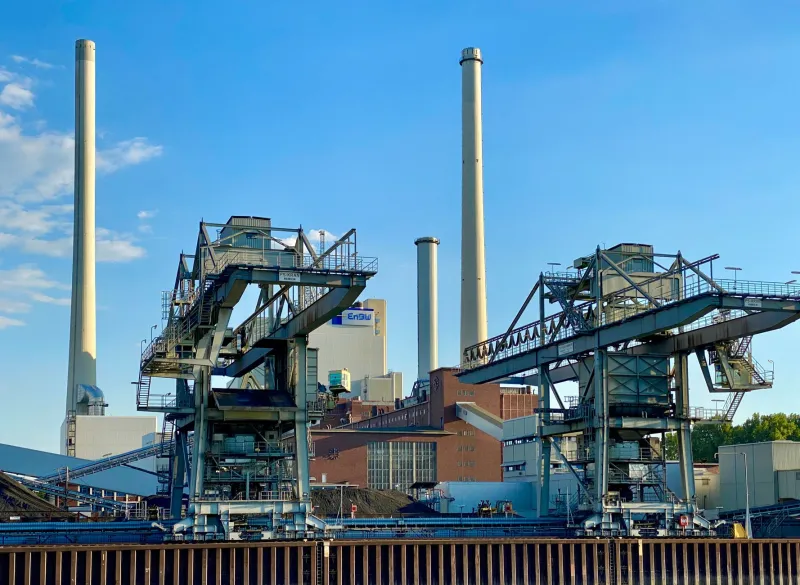
The arithmetic has become brutally simple for coal plant operators across the United States. Every month a facility remains on the books without a credible disposition strategy, its balance sheet contribution deteriorates further—squeezed between rising compliance costs, falling capacity market revenues, and a regulatory environment that grows less hospitable by the quarter. For utility executives and independent power producers managing aging coal portfolios, the question is no longer whether to act, but how fast and through which mechanism.
The scramble to monetize or responsibly exit coal assets has intensified sharply over the past two years, driven by a convergence of factors: tightening EPA emissions standards, state-level retirement mandates, pressure from institutional investors demanding portfolio decarbonization, and the straightforward market reality that coal-fired generation is increasingly uncompetitive against natural gas and utility-scale renewables. What's unfolding across the Midwest, Appalachia, and the Mountain West is a high-stakes financial exercise with no clean solutions—only varying degrees of loss mitigation.
The Depreciation Dilemma
For regulated utilities, the most politically and financially contentious question surrounding coal retirement is depreciation. Traditional rate-regulated frameworks allow utilities to recover the undepreciated value of generation assets through customer rates over the expected life of the plant. When a plant is retired early—whether voluntarily or under regulatory pressure—that remaining book value becomes a liability that must be resolved.
Accelerated depreciation, which allows utilities to write down asset values more rapidly before retirement, has emerged as one of the primary tools for managing this exposure. Several state utility commissions have approved accelerated schedules in recent years, recognizing that prolonged carrying costs for plants with limited operational futures create greater long-term harm for ratepayers than a structured write-down. However, accelerated depreciation is not without political friction. Consumer advocates frequently challenge the approach, arguing that ratepayers should not bear the cost of strategic decisions made by utility management decades ago.
The tension between these positions has produced inconsistent regulatory outcomes across jurisdictions, leaving plant owners in states with less progressive commissions in a particularly difficult position—unable to accelerate depreciation, yet facing mounting pressure to retire assets that are no longer economically or environmentally defensible.
The Sale Option: Buyers Are Scarce, and Getting Scarcer
For independent power producers not subject to rate regulation, the obvious exit is a sale. In theory, a willing buyer could acquire aging coal assets at a steep discount, operate them through remaining useful life, and manage decommissioning liabilities as part of the deal structure. In practice, the buyer universe has contracted dramatically.
Private equity firms that once circled distressed coal assets as contrarian plays have grown more cautious as merchant coal revenues have proven increasingly volatile and environmental liability exposure has become more difficult to quantify. The contamination risks associated with coal combustion residuals—fly ash ponds, landfill sites, and groundwater impairment—have added legal and remediation complexity that many prospective acquirers are unwilling to absorb without substantial indemnification from sellers.
Some transactions are still occurring. In the Ohio Valley and parts of the Southeast, smaller operators have acquired plants from larger utilities seeking to clean up their portfolios, often with seller financing and complex environmental indemnity arrangements. These deals are rarely straightforward, and they frequently transfer rather than resolve the underlying liability.
Repurposing: The Data Center and Clean Energy Pivot
Perhaps the most discussed—and most frequently overstated—alternative to outright retirement or sale is site repurposing. Coal plant sites carry genuine infrastructure advantages: robust grid interconnection, substantial acreage, water access, and in many cases, existing transmission capacity that would cost hundreds of millions of dollars to replicate elsewhere.
Data center developers and hyperscale cloud operators have taken notice. Several announced projects across states including Indiana, West Virginia, and Wyoming involve converting former or soon-to-retire coal facilities into high-density computing campuses. The logic is straightforward: data centers require reliable power delivery at scale, and coal plant sites often sit adjacent to transmission infrastructure capable of supporting that demand.
Similarly, some plant owners are exploring co-location of battery storage systems or small modular reactor development on retired coal sites, leveraging existing grid connections to accelerate interconnection timelines. These strategies, while promising in select cases, are not universally applicable. Sites with significant ash pond contamination, aging switchyards, or poor proximity to fiber infrastructure may offer limited repurposing potential regardless of their transmission assets.
The Hidden Cost of Delay
What the financial models often underweight is the compounding cost of indecision. Coal plants that continue operating past their economic optimum accumulate maintenance expenditures on equipment that will never be recovered through revenues. Environmental compliance costs—particularly around mercury, sulfur dioxide, and particulate standards—continue to escalate. And the longer a plant remains in regulatory limbo, the more difficult it becomes to attract qualified buyers, development partners, or favorable depreciation treatment from state commissions.
Utilities that moved decisively on coal retirement five years ago—securing accelerated depreciation agreements, negotiating environmental settlements, and locking in replacement capacity through long-term renewable contracts—are in materially better financial positions today than peers that delayed in hopes of a market reversal that did not materialize.
The lesson for operators still navigating this landscape is clear: the regulatory and market environment for coal assets is unlikely to improve, and each quarter of inaction narrows the range of viable options. Whether through structured depreciation, discounted sales, or creative site repurposing, the window for value extraction is closing—and the cost of missing it will fall squarely on balance sheets already under pressure.