Nowhere to Sell: How Stranded Legacy Assets Are Trapping Energy Companies in a Buyer's Desert
For years, the conventional playbook for large integrated energy companies navigating the energy transition was straightforward: divest the legacy infrastructure, redeploy the capital into cleaner assets, and let someone else manage the political and regulatory risk of running coal plants and aging gas pipelines into their twilight years. It was a tidy theory. The execution, however, is proving far messier.
Across the United States, energy firms are sitting on portfolios of aging infrastructure that they cannot sell at prices that make financial sense — and in some cases, cannot sell at all. The market for transition-incompatible assets has not merely softened. In several segments, it has effectively seized.
The Valuation Collapse in Real Time
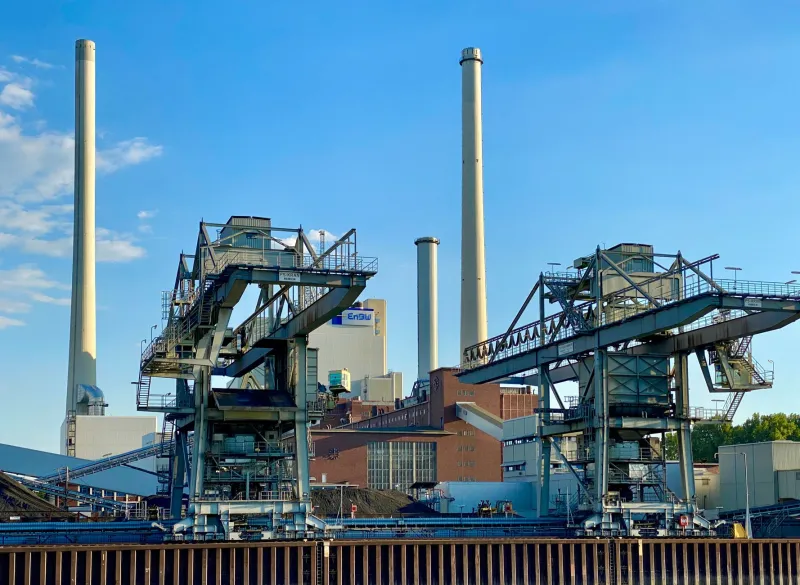
The mechanics of this impasse are not difficult to trace. Legacy coal plants, older gas peakers, and midstream infrastructure tied to declining production basins have all experienced significant valuation compression over the past three years. Buyers who once populated this space — merchant operators, private equity funds with long time horizons, and regional utilities seeking low-cost baseload capacity — have largely stepped back.
Private equity, which had been the most active acquirer of distressed energy assets through the mid-2010s, is increasingly selective. Funds that once viewed fossil fuel infrastructure as a cash-generating bridge to eventual redevelopment are now contending with their own limited partner pressure to demonstrate ESG alignment. The result is a compression of the buyer universe at precisely the moment sellers are most motivated to transact.
Valuation methodologies have also shifted in ways that disadvantage sellers. Discounted cash flow models applied to coal plants must now incorporate accelerated depreciation schedules, carbon risk premiums, and the growing probability of early regulatory retirement. When those adjustments are applied honestly, the gap between what sellers believe an asset is worth and what buyers are willing to pay can exceed forty percent.
The Holding Period Problem
What makes this dynamic particularly acute is the mismatch between holding periods and useful life. A coal plant that a utility acquired in 2005 with an expected operating life extending to 2040 may now face regulatory retirement pressure by 2030 — or sooner. The capital that was supposed to be returned to shareholders over a fifteen-year horizon is now compressed into a five-year window, under conditions of declining utilization and rising compliance costs.
For companies that borrowed against these assets, the situation is more precarious. Debt covenants structured around cash flow projections that assumed stable or growing capacity factors are being stress-tested by dispatch patterns that reflect a grid increasingly saturated with zero-marginal-cost renewables. When a coal plant that once ran at a seventy percent capacity factor is now dispatching at forty percent, the financial model underlying the original acquisition begins to break down.
Some companies have responded by attempting to reposition these assets — converting coal plants to gas, exploring co-firing arrangements with biomass or hydrogen, or pursuing site repurposing for solar or battery storage development. These strategies are not without merit, but they require additional capital investment, extend the period of uncertainty, and do not guarantee a path to liquidity.
Strategic Dead-Ends and the M&A Reckoning
The inability to execute divestitures at acceptable valuations is forcing a strategic reckoning in boardrooms and investment committees across the industry. Companies that had structured their transition roadmaps around asset sale proceeds are now confronting a funding gap. Capital that was earmarked for clean energy development is instead being consumed by the carrying costs of assets that refuse to find buyers.
This dynamic is beginning to alter the landscape of energy sector M&A in observable ways. Merger discussions that might once have proceeded smoothly are stalling when due diligence reveals the depth of legacy liability exposure on a target's balance sheet. Acquirers are demanding indemnification structures and escrow arrangements that sellers are reluctant to accept. Some transactions are being restructured as joint ventures rather than clean acquisitions, specifically to distribute the long-tail liability risk.
Regulators are not making the process easier. State public utility commissions in several jurisdictions have imposed conditions on asset sales that include minimum staffing levels, environmental remediation commitments, and operational continuity requirements that can extend years beyond the transaction close. These conditions, while understandable from a consumer protection standpoint, further reduce the pool of buyers willing to absorb the associated obligations.
The Liability That Outlasts the Asset
Perhaps the most underappreciated dimension of this problem is the persistence of environmental and decommissioning liabilities that survive the asset itself. Coal ash impoundments, contaminated sites, and pension obligations tied to legacy workforces do not disappear when a plant is sold or shuttered. In many cases, they represent the most significant financial exposure on a company's books — and they are extraordinarily difficult to transfer.
Several utilities that pursued aggressive divestiture strategies in earlier years have since faced legal challenges from state attorneys general and environmental agencies seeking to hold original owners responsible for remediation costs, even after ownership had technically transferred to undercapitalized buyers. These precedents have made sophisticated acquirers even more cautious about assuming legacy liabilities without robust structural protections.
The implication for energy companies still holding transition-incompatible assets is sobering. The window for orderly divestiture at reasonable valuations may already be closing. Each year that passes without a transaction is a year in which the asset depreciates further, the regulatory environment tightens, and the buyer pool narrows. The companies best positioned to navigate this challenge are those that accept the new valuation reality early, structure creative transaction mechanisms that distribute risk appropriately, and build decommissioning reserves before regulators mandate them.
For those still waiting for market conditions to improve, the arithmetic is unforgiving. In a sector being reshaped by capital allocation decisions made at the speed of policy, patience is not always a virtue.